saving

Why an Emergency Fund Matters – and How to Build One.

Life does not always give us time to prepare. A medical bill, a sudden job loss, or an urgent car repair can put pressure on your budget quickly, especially when the expense cannot wait. That is where an emergency savings fund can make a real difference.

WHAT AN EMERGENCY FUND CAN DO FOR YOU

An emergency savings fund can help you cover costs that need immediate attention and could have serious consequences if left unpaid. Think of it as a financial safety net. When used as intended, an emergency fund gives you more flexibility, more confidence, and more control during difficult moments.

  • Avoid acquiring new debt. Without a proper savings fund, many people turn to credit cards or personal loans in the event of an emergency. While these resources can provide immediate access to funds, they also come with interest fees that will make your emergency repayment more expensive over time.
  • Build financial security. A designated emergency fund helps pay for expenses without pulling from retirement savings or your long-term investments. It allows you to cover your needs now, without sacrificing the goals you’re already working towards.
  • Maintain personal wellness. Stress from finances can negatively impact your health, relationships, and goals. Knowing you are covered in the event of an emergency can make these situations less overwhelming.

WHEN AN EMERGENCY SAVINGS CAN HELP

Not every unexpected inconvenience is an emergency. Forgetting you scheduled an oil change for your car and needing an extra $100 for the appointment may be inconvenient or frustrating, but likely isn’t an emergency. It’s important to set guidelines for yourself or your household to ensure that your emergency savings fund achieves its’ goal.

Your emergency savings should come into play when the situation is urgent enough to require immediate attention, and may cause consequences if left unattended, such as:

  • Unexpected medical bills for you, your family, or a pet
  • Covering bills or living expenses after job loss
  • Home repair needs, such as unanticipated roof repair

HOW TO START BUILDING YOUR EMERGENCY SAVINGS FUND

Building an emergency fund will take time, but what’s most important is that you’re taking the first step. Take the task one month at a time and remember that each savings deposit you make is a small success that brings you closer to your wellness goals. 

1. SET A GOAL

Every situation – and emergency fund – is unique. To make a fund for your household, you must understand your regular expenses and responsibilities. A common standard for an emergency fund is to save enough to cover three to six months of essential living expenses. Think about what you are responsible for and what would need to be covered if your income was interrupted. Consider any dependents, mortgage or rent payments, bills or minimum debt payments, transportation, and food.

Choose a goal that fits your lifestyle – if your income is inconsistent, you’re preparing for a lifestyle change, or you take care of another family member, a larger fund can provide additional stability.

2. STAY CONSISTENT

Once you have a goal that fits your needs, make consistent savings a part of your routine. Steady contributions can add up overtime and create lasting, healthy financial habits. Set up automatic transfers that fit into your budget to ensure you pay yourself first.

  • Adjust your budget as needed. Small sacrifices to non-essential expenses will accumulate and could eventually cover your next unexpected cost.
  • Use unexpected income (such as a portion of a raise or what you receive from a tax return) to start or boost your savings fund.

3. REASSESS REGULARLY

Review your expenses regularly to ensure your emergency savings fund still fits your current needs. If you need to use any of our emergency funds, be sure to start replenishing what was used as soon as you can. Using the funds for an emergency is what your account was designed to do, and rebuilding it after ensures your safety net is still ready for the future.

HOW TO PICK THE RIGHT ACCOUNT FOR YOUR EMERGENCY SAVINGS

Accessibility is essential when choosing an account for your emergency fund. If accessing your money is difficult or subject to penalties at certain times, it might not serve you well in an emergency.

Look for an account that allows you to access your money without additional barriers. Watch out for account terms including penalties on early withdrawals, minimum account balance requirements, or limits on withdrawals per month.

At the same time, you may want to consider whether the account offers a higher savings yield than a standard savings account. This could help you reach your goal more quickly. Chaffey FCU’s Summer Savings Club offers a higher yield, includes automatic transfers into the account each month, and has no penalties for early withdrawals.

Emergency savings funds are about creating everyday peace of mind, and making urgent expenses easier to manage. Building an emergency fund may take time, but every deposit is progress. Starting now can help you and your family feel more stable and focused on your long-term goals.
Creative Spending Strategies

When building a budget that prioritizes your future self, contributions to your savings are a necessity. Discovering savings opportunities in your existing spending habits can lead to personal wins that help you maximize your own financial wellness. To help you uncover these opportunities, we’re providing insight and creative savings strategies to test out for yourself.

Prioritize Your Grocery List

We’ve all been there before: at the grocery store on an empty stomach when we fall victim to stocking up on snacks and meals we don’t need (but sound delicious!). Don’t underestimate the impact that building a well-thought-out grocery list can have on your account balance – those last-minute additions can add up quickly.

Before building your list, check what you already have at home! Chances are, you already have some food that you can incorporate into your meals this week.

If you plan to shop at a store that has an app or a web version, you can build your cart online beforehand to see how much it will cost to avoid expensive mistakes at check-out.

Make a List of Your Impulsive Wants

If you see something you want when you’re out shopping, but it’s not something you budgeted for nor is it something you or your household need right away, add it to a wish list to revisit later.

At the end of the month, review everything you listed to determine what you still want (and have enough money) to purchase. By then, it’s likely you won’t still want everything you saved, so it will be easier to narrow down the items and avoid regretful purchases.

Review Subscriptions

Everything is available as a subscription service these days: entertainment at home, grocery orders, or hobbies and clothing delivered to your doorstep. Review the subscriptions you already have – do you know how much you spend each month on these services?

  • Services you don’t use each month. Why pay regularly for something you haven’t used in months?
  • Services that are similar. Choices are essential in entertainment, but do you need five television streaming services? Narrow down your top one or two services to give yourself some choice, while limiting the effects on your budget.
  • Services that have more affordable options elsewhere. Instead of clothing or beauty subscriptions to try new things, opt for online blogs, social accounts, or thrifting to find new inspiration. Many local libraries offer free access to digital services with books, streaming, and music for anyone with a library card to enjoy.

Pause your existing plans with subscriptions you don’t use or want – you can always sign up again later when you want to try them out again! Choosing what to keep may require some compromise if you share these services with your family. Look for services that multiple people use. You can always switch which ones you use every few months to meet everyone’s wants.

Start Automatic Savings

Starting your savings can be difficult. When you’re already stretching your monthly budget, setting money aside can feel out of reach. Automatic savings transfers can help you build the habit of “pay yourself first.” Set up automatic transfers each month on a specific day or use payroll deduction each time you get paid to ensure you’re prioritizing your future wellness. Remember: YOU are the most important bill that you have to pay!

Unexpected expenses happen to all of us when we least expect them – when that happens, it is better to have funds in your savings account already, instead of building unnecessary debt or taking on additional stress. You can always adjust the amount you save to fit your needs once you set this up.  

Look for Cash Back & Coupon Benefits

Cash Back or Coupon opportunities are available everywhere these days if you know where to look for them. Searching for available savings opportunities can help you save on items you plan to purchase anyways.

  • Visa Rewards Points. If you have a Chaffey FCU credit card with Visa Rewards, put your budgeted purchases on that card and pay it off at the end of the day or week. You might as well earn extra rewards or cash back on your regular purchases.
  • Benefits Checking Accounts. Many checking accounts, like Chaffey Plus Checking, offer in-app cash back or shopping rewards for purchases made through its’ online shopping portal.
  • Online and Mail Coupons. Most stores have online pages dedicated to current specials, coupons codes, or other savings opportunities. Mail circulars or coupon apps can provide additional places to search for discounts.

Try out the envelope method

If you are more of a visual learner, the envelope method can help you stick to your budget. Before each month begins, put your allocated money aside into envelopes for each spending category (such as, groceries, rent, car expenses, entertainment or vet bills). When your funds in each envelope run out, your spending for that category should stop until next month.

If you want to try this method, but don’t want to handle so much cash, you can replicate this process with sub-savings accounts. Open sub-savings accounts for each budget category and transfer budgeted funds into each account at the beginning of the month.

Slow Down Your Transportation (and Stay Cool!)

Did you know, driving faster can reduce your gas mileage? On average, vehicles typically see a decrease in fuel economy after passing 50 MPH. When on the highway, utilizing cruise control can also help you optimize gas usage and overall savings. Choosing to slow down and avoid excessive acceleration is a surprising way to help you stretch your fuel usage and save more money. During the heat of the summer months, fill up your tank in the morning when the gasoline is cooler.  As gasoline heats up it expands, so filling up during the hottest part of the day means you actually are getting less.

Pre-Plan Your Usage for Major Appliances.

Using major appliances during peak times of the day (usually evening times such as 4pm – 9pm) can inflate your energy bill, since that’s when most people are also using more energy. When possible, planning to use major appliances earlier in the day can help you save on your energy bills. Many appliances have a delayed start feature, so you can set the dishwasher to run before you go to bed and still wake up to clean dishes!

Extend Out Your Dine Out

Sometimes a busy schedule can get the best of you, and you find yourself eating on the go instead of cooking at home.  When this happens, consider the portion sizes of what you are ordering.  Oftentimes a meal purchased at a restaurant or at the drive-thru can be split into multiple meals and still give you the energy you need.  You can also take advantage of free refills for drinks to go and turn that $4 cup of soda into two $2 cups of soda!

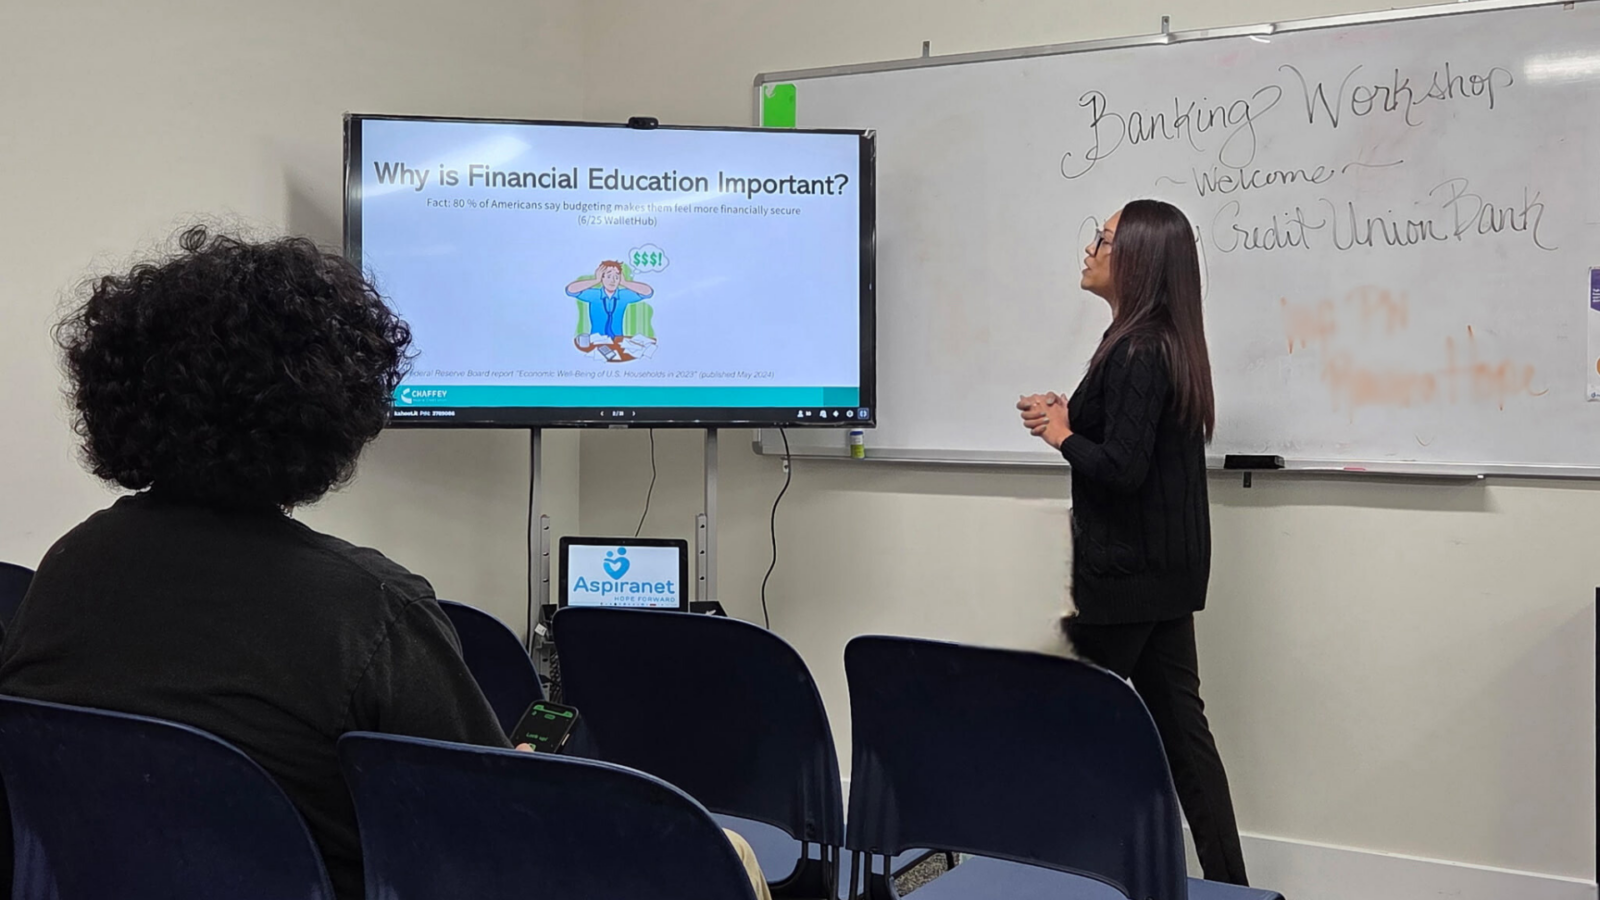
Financial Education: Aspiranet

Asipranet works to provide foster and adoption support, residential group homes, and other health services across California. We’re proud to have offered financial education to teens and young adults at their Redlands location.

Start Saving for Your First House

The thought of buying a home can be overwhelming, especially for a first-time homebuyer.  Your home is most likely the largest purchase you will make in your lifetime, and we want to help put you in a position where you can enjoy your investment for many years to come. A disciplined savings plan can be good practice for you and your budget not only to reach your savings goal, but also to be prepared with the extra expenses that come along with home ownership.  Buying a house before you (or your savings account) can handle it can interrupt your entire plan.

Set a Savings Goal

To make the journey more feasible, know how much you want to save. Having an attainable goal that you can track will help you plan how quickly you can get into your new house. If you know how much you need to save you can also adjust your savings contributions and budget as needed to reach your goal more quickly.

Consider your downpayment, closing costs, and moving expenses when building your savings goal – you’ll need to be able to cover these costs when you first purchase your home. Your downpayment is the upfront cash you put down to buy your house, and the rest of the purchase price is financed. Knowing if you want to put down 3% (the Chaffey FCU minimum requirement), or 20% (which could in result in a more favorable monthly payment and rate) will impact how much you need to save now.

Closing costs are the fees needed to finalize your mortgage, and these are paid by you in addition to the down payment. They cover the additional expenses associated with purchasing your home, such as loan origination (or the approval process for your mortgage), appraisal fees (to confirm the value of the home you’re looking to purchase), property taxes, and any applicable insurances. Together, closing costs typically account for 2-5% of your total home cost, but can still vary based on your specific home-buying situation. If you are looking for a more detailed review of what might be included in your closing costs, or how expensive they might be, connect with our Lending team today.

You can also look to family or your local community for down payment resources. First-time homebuyers often receive down payment funds as a gift from family members; if this is part of your plan, make sure you understand some of the rules and documentation that gifted funds require.  Down payment assistance programs through the Federal Home Loan Bank and other local partners may be available, but keep in mind that eligibility requirements can be strict and funding may not always be available when you are in the market.  That being said, do your research and know what programs are available to you, because you may be in just the right spot at the right time!  And finally, sometimes your realtor can help you negotiate for the seller of the property to pay the closing costs, which can reduce the amount of cash you need to provide out-of-pocket.  Of course, being able to cover your own closing costs puts you in a stronger bidding position to purchase the property, so we do not recommend relying on this option as a guarantee.

If you need help determining what you can afford as you build your budget or savings plan, Chaffey FCU offers free Home Lending Calculators to help you determine how much home you can afford or what your mortgage payments might be.

Reduce your debt, Increase your savings

Saving up for a house is no easy feat. With how expensive the current housing market is, many think that saving for a house is an impossible task, but don’t let that discourage you. There’s a lot you can change in your regular routine to help you reach your goal.

Refinancing auto loans, consolidating debt, or committing to a debt repayment plan can go a long way in maximizing the amount of money you are able to put into savings. Plus, minimizing your debt before applying for a mortgage can improve your credit score and decrease your debt-to-income ratio, which can help improve the terms and affordability of your home loan.

When you receive additional funds, such as a work bonus or raise, add them directly into your housing fund for an extra boost. If you find yourself struggling to commit to your monthly savings goal, automating your savings contributions can help take the stress off yourself. Out of sight, out of mind.

Savings Accounts that help you earn more

Once you have started setting funds aside for your home, putting them in an account that earns a higher yield can be an easy way to start earning more on your existing savings.

  • Share Certificates are an easy tool to lock in savings to earn a higher rate. Chaffey FCU Share Certificates only require a minimum balance of $1,000 to help you make the most of your savings, even if you’re just starting out. However, if you open your Certificate with a minimum balance of $10,000, you can expect to lock-in an even higher savings rate.
  • If you want to earn more than what is offered by a traditional savings account, but don’t like the idea of locking your funds away for the entire term of a Share Certificate, Money Market accounts offer a higher yield with the liquidity of a checking account.
  • If you are looking for something with a higher return or more flexibility, speaking with a professional about investment options might help you build your savings strategies in the long-run.

Know what you’re saving for

Understanding your wants and needs in a new home can help you better understand how much you should be saving and budgeting for. The type of house or the neighborhood you want to live in can have a big impact on how much you need to save.

Searching online and touring houses in-person can help you understand the true cost of your dream home. Sometimes, this search might also help you realize that refining your home “wish-list” is a realistic step on your home ownership journey. Ask yourself questions such as:

  • How much space will you need in your house?
  • Do you want to take on a house that might require home improvement projects?
  • Are you willing to commute to work?
  • What neighborhoods or school districts do you want to be in?

If you’re getting ready to take the next step in your home-buying journey or are looking for some more expertise as you determine how much you should be saving, the Chaffey FCU Loan Department is ready to assist you through your unique home-buying needs. Contact us today or submit a Real Estate inquiry form to get the conversation started.

You are leaving the Chaffey Federal Credit Union website

You are being directed to a third-party website.

Please note that this third-party website is not controlled by Chaffey Federal Credit Union or subject to our privacy policy.

Thank you for visiting our site. We hope your visit was informative and enjoyable.